Oil and the geopolitics of a fractured world
Oil prices will rise and fall. The difficult questions are how far they will move, what will drive them, and who will pay for the uncertainty. In the present crisis, a forecast of continued volatility is more defensible than a confident prediction of where Brent will stand on a particular day. Even volatility, however, cannot be reduced to a promise that every trading session will produce the same large swing.
My starting argument is that the oil crisis will outlast the announcements intended to contain it. A Russian diesel agreement, an emergency release or reassuring diplomatic language can provide relief. None, on its own, repairs refineries, protects export terminals or makes commercial shipping safe. The forces keeping oil expensive are spread across several conflicts and several stages of the supply chain.
That is why this is a story about much more than the price of a barrel. Oil connects military strategy with the cost of delivering food, sanctions with election campaigns, and regional conflict with decisions about the cars people buy. A government can pursue victory abroad while creating economic pressures that undermine its freedom of action at home.
The central uncertainty is whether these pressures will produce an accommodation that restores supply, or further escalation that damages it. This article examines both possibilities. Its judgments about future events are conditional; reported developments are attributed to sources, and claims made by governments at war are identified as claims.
The crisis has several distinct parts
The word oil hides important differences. Crude is a raw material. Diesel, petrol and jet fuel are manufactured products. Refineries convert crude into these and other products; their output depends on the plant, the feedstock and operating decisions.[1] A country can therefore have crude available while experiencing a shortage of usable fuel.
For an oil-producing country, the relevant questions are separate. Can it extract crude? Can it process the crude? Can it transport either the raw material or the finished product? Can buyers pay for the cargo and obtain the services needed to deliver it?
A change at one stage does not automatically solve problems at the others. Sanctions relief may reopen a commercial route without restoring a damaged processing unit. More production may increase available crude without increasing diesel supply by a corresponding amount. A repaired refinery may remain constrained if its export terminal cannot operate safely.
This distinction changes how we should read political announcements. A promise of additional diesel should be judged against the diesel shortage, its delivery timetable and the supply that would otherwise have reached buyers. It should not automatically be translated into an equivalent increase in daily crude production.
It also helps explain why consumers can remain under pressure while Brent falls. The benchmark price is only one component of the cost of delivered fuel. Processing, transport, taxation and distribution intervene between the barrel and the customer. Reuters columnist Ron Bousso has emphasised the current importance of freight, insurance and refining bottlenecks.[2] The implication is that a fall in crude may provide incomplete relief at the pump.
Russia and America are negotiating under different pressures
The newly announced Russian diesel arrangement exposes a contradiction in American policy. Washington wants to constrain Russia’s ability to finance its war, while also seeking additional fuel that might lower costs for American consumers. Reuters reports both the agreement and analysts’ doubts that its volumes can deliver sustained price relief.[3]
My interpretation is that fuel scarcity has increased Moscow’s negotiating value. A supplier under sanctions becomes harder to isolate when importing countries urgently want its products. The resulting accommodation may be economically understandable and strategically costly at the same time.
Critics can reasonably call this appeasement if they believe Washington is relieving pressure on Moscow without securing a meaningful concession on Ukraine. Supporters can argue that managing an immediate shortage is necessary even when the supplier is an adversary. Neither position answers the practical question of how much additional fuel will actually arrive.
The political argument and the physical supply argument must therefore be assessed separately. A deal can benefit Russia diplomatically without transforming the market. It can modestly improve supply while damaging confidence in sanctions. It can also be valuable to a US administration precisely because it produces an immediate announcement, even if the full economic effect takes longer.
We should be careful with the word additional. Cargoes redirected from one buyer to another do not necessarily expand worldwide availability. Restoring exports that had genuinely been withheld would have a more substantial effect. The balance between those two possibilities depends on Russia’s production, domestic requirements and actual shipments.
Damage to Russian refineries matters without proving collapse
Ukraine’s attacks on Russian refining infrastructure are an important part of this calculation. AP reported on 5 October that Ukraine claimed to have disabled 51 per cent of Russian refining capacity. AP explicitly said the claim could not be independently verified. The same report described fuel shortages and restrictions on sales, while noting the absence of comprehensive Russian damage figures.[4]
The responsible conclusion is that the disruption is significant and its exact scale uncertain. It is not that Russia has no oil left to export. Damage to refining capacity is different from the disappearance of crude production, and announced capacity losses are different from measured losses of finished fuel over a sustained period.
This matters politically as well as economically. In principle, a Russian government facing insufficient fuel must decide how to distribute it between civilian consumers, commercial activity, military requirements and exports. Export earnings may strengthen the state financially while local shortages weaken public confidence. Those objectives can pull in different directions.
However, hardship does not provide a reliable timetable for political destabilisation. Shortages can generate anger without generating organised opposition. The state may shift supplies between regions, ration access or prioritise essential activities. Evidence of economic pressure should not be presented as proof that the political system is close to breaking.
The practical challenge is recovery. Even a durable pause in attacks would stop new damage before it reversed old damage. In my assessment, the important test is sustained output after repair, rather than the announcement that a plant is restarting. An installation can return partially, encounter technical problems or face another attack.
For the market, a credible recovery would involve several weeks of dependable production and deliveries. For Moscow, it would also involve enough domestic availability to make continued exports politically manageable. Those conditions cannot be created by removing a legal restriction alone.
Ukraine and the United States do not have identical objectives
The Financial Times has reported US pressure on Kyiv to halt refinery attacks, including a threat concerning intelligence sharing.[5] The significance is not merely disagreement between leaders. It is a difference between the priorities of a country defending itself and those of a powerful supporter managing wider economic consequences.
From Kyiv’s perspective, disrupting infrastructure that supports Russia’s war can be a way to impose costs beyond the battlefield. From Washington’s perspective, those same disruptions can worsen fuel scarcity and increase domestic political pressure. These are analytical interpretations of the competing incentives, not evidence that either side has only one motive.
A proposed pause consequently raises difficult questions. Would it be reciprocal? Which facilities would be protected? Would Russia obtain a recovery period without an equivalent benefit for Ukraine? How would compliance be verified? What would happen after a breach?
A temporary accommodation could help repair activity and reduce uncertainty. It could also fail if either side believed that the other was using restraint to improve its military position. Energy diplomacy is therefore bound up with the credibility of the wider security arrangement.
An American fuel problem cannot simply erase Ukrainian security concerns. Equally, Ukraine cannot assume that the economic consequences of its strategy will be irrelevant to its supporters. Oil makes this tension visible because the consequences reach voters and businesses far from the war.
Hormuz remains the most important physical vulnerability
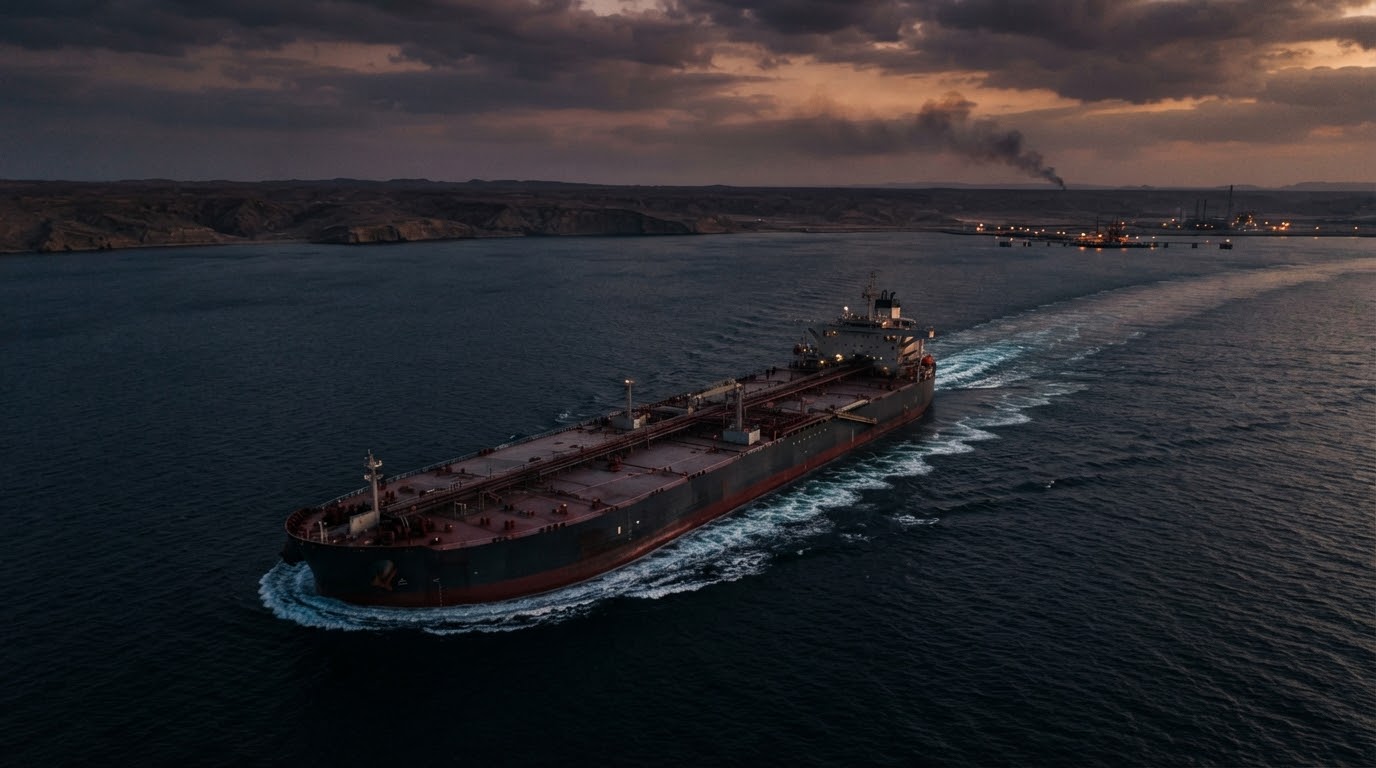
The strongest part of the case for persistent instability concerns export routes. The IEA identifies Hormuz as the principal route for oil from several Gulf producers and warns that prolonged disruption could make much of the world’s spare production capacity unavailable.[6]
That does not require the strait to be completely closed at every moment. Commercial confidence can deteriorate even when some tankers continue to pass. Buyers must consider delays, the risk of losing a vessel or cargo, and whether the next shipment will arrive. An intermittent route can therefore remain economically disruptive.
This is where a military confrontation becomes a global supply problem. Oil below ground has limited immediate usefulness to a distant refinery. Available production capacity provides less reassurance if there is no dependable way to deliver its output.
The diplomatic test is correspondingly practical. A statement about reopening a route matters most when followed by repeated safe voyages, reduced interruptions and commercially workable arrangements. One successful transit cannot establish lasting normality; equally, one attack does not prove that every future shipment is impossible.
My assumption is that restoring trust will take longer than securing the first successful cargo. Operators need evidence that an accommodation will survive political disputes and military incidents. This is one reason a headline-driven fall in prices may reverse before physical supply has changed substantially.
Saudi Arabia has influence but cannot set the world price alone
Saudi Arabia’s potential contribution should be understood through spare capacity and deliverable exports. Its production costs are relevant to commercial resilience, but cheap extraction does not mean a government will choose a cheap selling price. Nor does it ensure that additional output can reach the market.
There is also an important difference between increasing an output target and delivering more barrels. Reuters reported that OPEC+ kept November targets unchanged and that much of this year’s announced growth had remained on paper because of the conflict.[7]
My conclusion is that the immediate constraint is not simply an unwillingness to pump. Export reliability can determine whether additional production is useful. Where storage and shipping are constrained, increasing output can create another bottleneck rather than immediate relief.
Nevertheless, Saudi Arabia is not the only actor capable of exerting downward pressure. Other suppliers, emergency stocks and reduced consumption can affect the balance. A sufficiently severe economic slowdown could lower prices even if Saudi exports remained impaired.
That possibility is unpleasant but important. Prices can fall because supply improves or because consumers become unable to afford their previous level of consumption. Both outcomes reduce pressure on the market; only the first necessarily represents a healthier economic situation.
The Houthis complicate any simple route to stability
The latest escalation in Saudi Arabia demonstrates the wider regional danger. AP reported that a missile attack on Riyadh airport on 10 October killed 12 people and injured more than 300. Saudi authorities blamed the Houthis, and the United States was considering a possible response.[8] An airport strike is not itself proof of lost oil production, but it can alter expectations about the security of other infrastructure.
The relevant market question is whether attacks remain limited or extend to facilities essential to exports, processing and transport. Retaliation could reduce the capacity to attack. It could also encourage further escalation. Neither outcome should be assumed in advance.
The argument that the Houthis cannot be defeated needs a definition of defeat. Eliminating an organisation, reducing its missile capability and establishing dependable commercial transit are different goals. A force may survive politically while losing some ability to disrupt shipping. Conversely, substantial military damage may leave enough capability for occasional costly attacks.
Iranian support is relevant to the wider strategic relationship, but the future intensity of that support should not be treated as unlimited or inevitable. Access to equipment, logistics, local decisions and wider diplomatic incentives all matter.
For oil, the problem is the possibility of continued disruption at a scale that is militarily survivable for the attackers but commercially expensive for everyone else. An agreement addressing Iran alone may leave questions about enforcement across the region.
Israel and Iran introduce another source of uncertainty
The assumption that Israeli military priorities may remain in tension with American efforts to lower fuel prices is plausible. Allies can share broad security concerns while disagreeing about acceptable risks, timing or the conditions for stopping military action.
But the proposition that Israel will continue until it achieves its aims is not a complete forecast. We must ask which aims, how success is defined, and what costs its government would tolerate. Military objectives can change, compromises can emerge, and domestic or international pressure can affect decisions.
Iran also faces choices. A strategy that imposes high costs on opponents may simultaneously damage its own economy or relations with important buyers. The leverage produced by disruption does not remove the costs of using it.
My concern is that an arrangement sufficient for one participant may be insufficient for another. A pause that benefits consumers might be rejected by an actor that considers its security objectives unfinished. That creates the possibility of partial agreements followed by renewed instability.
It would nevertheless be inaccurate to describe conflict as inevitable or diplomacy as useless. A limited agreement can improve the movement of oil without resolving every regional dispute. The degree of improvement depends on its scope, enforcement and durability.
Elections matter without explaining everything
The approach of America’s 3 November midterm elections adds an immediate political incentive to reduce fuel costs. High prices affect households directly and businesses through operating expenses. The significance of the electoral pressure is documented in reporting on the diesel negotiations.[3]
My interpretation is that the election timetable can encourage measures offering quick, visible relief. The effects of those measures may extend beyond the election itself. A temporary commercial opening can create beneficiaries, expectations and contracts that become costly to reverse.
There are at least two plausible paths afterwards. Washington might restore pressure on Moscow once the immediate political urgency declines. Alternatively, continuing shortages could make renewed restrictions economically unattractive. The administration could also combine selective exemptions with sanctions elsewhere.
We should therefore resist the prediction that a post-election reversal is automatic. Its likelihood depends on fuel availability, congressional pressure, developments in Ukraine and the administration’s wider bargaining strategy.
European policy may follow a different course. Reuters reports that Germany has reaffirmed its commitment to sanctions despite the American announcement.[9] This illustrates a further complication: an exemption in one jurisdiction does not establish worldwide agreement about trade with Russia.
China can ease shortages without ending the crisis
China’s planned October refined-fuel exports total approximately 3.7 million tonnes, according to Reuters.[10] Their effect should be evaluated as relief to particular product markets, not as a comprehensive settlement of the crude-supply problem.
My assessment is that even partial relief matters. If additional products reach buyers who would otherwise compete for scarce cargoes, pressure can decline. But scale, composition and timing determine how much. A mixed product total cannot be treated as though every tonne were diesel.
Exports also depend on domestic conditions. A government seeking both affordable local fuel and influence abroad may change its priorities when shortages develop. Commercial availability is therefore connected to national policy, not only to refinery capability.
This gives China an interest in diversified supply and reduced oil dependence. It does not imply that its export decisions can overcome every loss elsewhere. The correct comparison is between the extra usable supply and the shortage it addresses.
Emergency stocks can buy time
The IEA’s statement of 7 October contains an important clarification. Members supported accelerating releases already pledged under the March collective action, with diesel prioritised where possible. Approximately 325 million barrels had already been released; fulfilling remaining pledges could bring roughly another 100 million barrels to market. That should not automatically be described as a wholly new commitment of 100 million barrels.[11]
For my analysis, the value of reserves is the breathing space they provide. A release can bridge a temporary interruption, moderate competition for cargoes and give diplomacy or repairs time to work. It cannot permanently substitute for recurring production and processing.
The distinction between stock and flow is essential. A finite number of barrels is useful in relation to a continuing shortfall, but its significance depends on how quickly it becomes available and how long the shortfall lasts. A large announcement may provide limited immediate relief if delivery is slow.
Reserve policy also involves a future choice. Stocks used now may eventually need to be replenished. Governments must balance immediate hardship against the need to retain protection from another disruption. The more persistent the crisis, the more difficult that balance becomes.
High oil prices spread costs far beyond motorists
Petroleum products support freight, agricultural machinery, aviation and industrial activity, as well as private transport. They also serve as feedstocks and materials in other applications.[12] The burden of expensive oil therefore reaches people who neither own a car nor follow commodity markets.
The economic consequences are uneven. A business able to pass higher costs to customers may protect its margin, while one facing weak demand may absorb the increase or reduce activity. A household with spare income can adjust more easily than one already choosing between essentials.
For governments, relief measures redistribute costs rather than making them disappear. A subsidy can lower the price paid by the consumer while increasing the public bill. A tax reduction can provide relief while reducing revenue. Measures aimed at vulnerable users may avoid some of the cost of broad support, but are harder to design and administer.
My expectation is that prolonged disruption would increase pressure for policies that reduce consumption as well as policies that increase supply. That can include efficiency, alternative transport and changes in purchasing decisions. Economic stress can accelerate adaptation, although it can also deprive households of the money needed to make that adaptation.
Electric vehicles change the longer argument
The strongest long-term element of this outlook is that unreliable fuel supply can encourage consumers and governments to reduce oil dependence. The IEA estimates that EVs avoided about 1.7 million barrels a day of oil consumption in 2025 and projects roughly 5 million barrels a day by 2030. These figures measure displacement against consumption without those vehicles; they are not a guarantee that total oil demand falls by the same amount.[13]
The process takes time because new vehicle sales change the existing fleet gradually. Expensive fuel can make an electric vehicle more attractive to a buyer who can afford it and charge it conveniently. It does much less for a household unable to replace its current car.
The same distinction applies to policy. Restrictions on future sales of certain vehicles are different from prohibiting fuel use in vehicles already on the road. National and local approaches vary; there is no single global ban on oil.
Electrification also creates requirements of its own. Consumers need electricity, charging access and suitable vehicles. Policymakers must consider the reliability of those systems rather than assume that substituting one energy source automatically eliminates vulnerability.
Still, repeated oil shocks can alter the calculation. Avoiding dependence on a disrupted maritime route may become an energy-security objective alongside cost and environmental goals. A transition driven partly by insecurity could persist even after fuel prices decline.
That is a plausible unintended consequence of the crisis. It is not evidence that Israel is maintaining conflict in order to promote electric vehicles or undermine oil-producing adversaries through future demand reduction. Assigning that motive would require evidence that is absent from the material examined here.
Less oil demand does not guarantee peace or permanently cheap oil
If electrification reduces demand growth, exporters may face greater competition for buyers. Some may seek to protect revenue by reducing supply. Others may compete more aggressively on price. Investment decisions would also respond.
This creates a potential counterforce to falling demand. Lower expectations can discourage investment in future production, reducing the cushion available when a disruption occurs. Whether the outcome is cheaper oil or renewed scarcity depends on how supply adjusts as well as on how consumption changes.
The geopolitical consequences are equally uncertain. Lower revenue could constrain a state’s military spending, but it could also intensify domestic pressure or encourage risk-taking. The ability to wage war depends on institutions, external support, priorities and existing resources as well as current export earnings.
The claim that cheaper oil will make Israel’s adversaries economically unable to fight is therefore too strong. A narrower argument is defensible: sustained reductions in petroleum revenue could weaken the financial flexibility of states that depend heavily on it. What they do in response cannot be read directly from the oil price.
Four possible paths from here
The following scenarios describe mechanisms, not calibrated probabilities or guaranteed price targets. From mid-October, a three-to-four-month horizon extends into January or February 2027; the remainder of 2026 is a shorter period.
Persistent disruption with intermittent relief
This is my working scenario. Export routes remain unreliable, damaged facilities recover unevenly and policy interventions prevent some shortages without restoring normal conditions. Agreements produce temporary optimism, followed by renewed concern when implementation disappoints or another attack occurs.
Brent could remain expensive in this setting without rising continuously. Declines would be entirely compatible with the broader argument. The latest EIA outlook, as reported by Reuters, envisages a fourth-quarter average of $105 and an average of $84 in 2027 as conditions improve.[14] Those are forecasts, not floors.
The evidence supporting this scenario would be continued inventory pressure, expensive delivered fuel and repeated interruptions to exports. Sustained safe transit and dependable refinery recovery would weaken it.
A workable accommodation and improving supply
Under a more favourable path, limited agreements protect enough shipping and infrastructure to permit gradual recovery. Russian product deliveries prove dependable, exporters adapt successfully and fewer fresh attacks interrupt repairs.
Oil could fall before every political dispute is settled. Markets would respond to improved delivery expectations, while consumers might receive relief more slowly as other costs adjusted. This is the strongest counterargument to the belief that unresolved war necessarily keeps Brent above $100.
A return toward $70–$80 would become more plausible if supply recovered sufficiently and inventories rebuilt. It would still depend on demand and producer decisions. The strongest evidence would be repeated deliveries and improving stock levels rather than a single diplomatic statement.
A wider confrontation and renewed scarcity
A less favourable path involves attacks on major export or processing infrastructure, a deterioration in shipping safety or a broader military response. Emergency releases could moderate the immediate effect without replacing sustained losses.
Prices could then rise substantially beyond recent levels. But the duration of a spike would depend on damage, alternative routes and consumption. Announcing a dramatic target without identifying the missing barrels would add confidence rather than understanding.
This scenario would be strengthened by independently confirmed outages and sustained reductions in deliveries. It would be weakened by evidence that disruption was brief or that alternative suppliers covered the loss.
Economic weakness lowers demand
A fourth possibility is that expensive energy and wider financial pressures reduce activity enough to bring consumption down. Oil prices could decline even while political risks remained serious.
That would bring some relief to buyers, but it would not necessarily be a success story. Lower demand could reflect reduced production, weaker trade or households cutting essential travel. A recovering economy might subsequently restore some of that demand.
This path would be supported by broad evidence of lower consumption and weaker activity, not merely a fall in Brent. It could also coexist with tight diesel markets if processing constraints persisted.
What would make us change our judgment
A useful outlook should explain what could prove it wrong. My view of persistent instability would weaken if shipping became reliably safe, refining output recovered and inventories rebuilt over a sustained period. It would strengthen if repeated attacks prevented repairs or additional sanctions reduced usable exports without replacement supply.
The most informative indicators are therefore physical: cargo loadings, arrivals, actual refinery output, inventories and transport costs. Diplomatic announcements matter because they can alter those conditions, but implementation is the test.
For traders, volatility creates movement without creating an assured profit. A correct geopolitical judgment can still produce a loss if the move was already anticipated, the contract behaves differently from the benchmark or the position cannot survive an adverse swing. A $3–$4 daily range is possible; it should not be treated as a guaranteed daily closing change.
For governments and households, the stakes are wider. The question is how long essential activity will remain exposed to military decisions made far away, and what investments can reduce that exposure without creating unaffordable new burdens.
My central expectation remains that physical recovery will be slower and less orderly than political announcements imply. The strongest challenge to that view is the industry’s capacity to adapt and governments’ incentive to reach limited accommodations. Both deserve attention.
Oil will continue to move between competing pressures: the urgency of today’s shortage, the bargaining power it gives suppliers, and the effort to reduce dependence tomorrow. The next agreement may matter. What matters most is whether it produces dependable energy where people actually need it.